Retirement early does not mean receiving a maximum pension of 75%
Besides age conditions, social insurance participation time directly affects the pension benefit rate.
According to Article 66 of the 2024 Law on Social Insurance, female workers are entitled to 45% of the average salary as the basis for social insurance contributions corresponding to 15 years of contribution, after which each additional year of contribution is calculated with an additional 2%, up to 75%.
For male workers, the level of 45% corresponds to 20 years of social insurance contributions, then each additional year of contribution is calculated with an additional 2%, the maximum level is 75%. For male workers with 15 years to less than 20 years of social insurance contributions, the starting benefit level is 40% corresponding to 15 years, then each additional year of contribution is calculated with an additional 1%.
This regulation shows that "being able to retire early without being deducted the rate" does not mean that everyone is entitled to a maximum level of 75%. The actual rate also depends on the number of years of social insurance contribution of each person. Therefore, before deciding on the retirement time, employees need to fully compare the process of social insurance participation with the conditions applied to themselves.
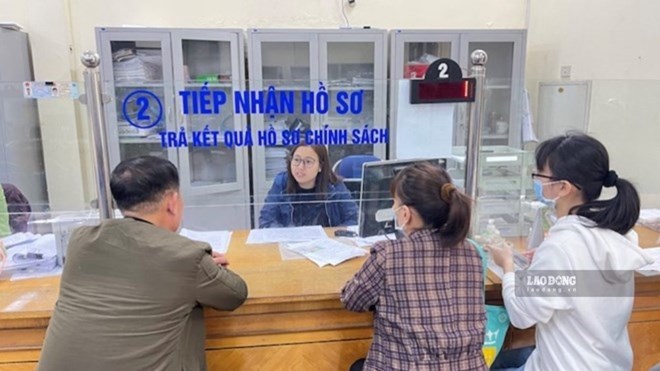
The 2024 Law on Social Insurance also opens up many methods of receiving pensions, creating convenience for beneficiaries. Employees can choose to receive them through bank accounts, directly from social insurance agencies or service organizations authorized by social insurance agencies according to regulations.
The important point that employees need to distinguish between is retiring at a lower age according to the conditions specified in Article 64 and retiring due to reduced working capacity according to Article 65. The two cases have different ways of determining conditions and benefit rates. Specifically for people retiring due to reduced working capacity, Clause 3, Article 66 clearly stipulates the principle of reducing the rate according to the time of early retirement.
Therefore, before carrying out procedures to enjoy the retirement regime, employees should carefully check the number of years of social insurance contribution, age, time working in heavy and hazardous occupations, and work area with their group of subjects. Determining the correct basis for retirement has direct significance for the benefit rate, thereby ensuring full pension benefits for a long time after leaving the labor market.
See the original here