Workers over 40 years old worry about losing their jobs, difficult to wait for retirement age
Not only teachers, many direct production workers are also in a situation where they have enough years of social insurance (BHXH) contribution but have not reached retirement age.
From the reflection of National Assembly Deputy Nguyen Ngoc Ha (Quang Tri Delegation), a noteworthy issue in the current pension policy can be seen: The minimum social insurance contribution period to receive a pension has been reduced from 20 years to 15 years according to the 2024 Social Insurance Law.
This condition is designed to expand the opportunity to access pensions, but when applied in practice, it reveals situations that are not really harmonious between professional characteristics, age and the ability of workers to continue working.
According to delegate Nguyen Ngoc Ha, pension policy needs to consider this harmony, especially in the context that the minimum contribution period is reduced but the retirement age continues to increase according to the roadmap. This creates a large gap between the minimum insurance contribution period and the retirement age as prescribed.
Reality shows that for teachers entering the profession from the age of 19-20, accumulating enough 30-35 years of social insurance contributions when just over 50 years old is possible.
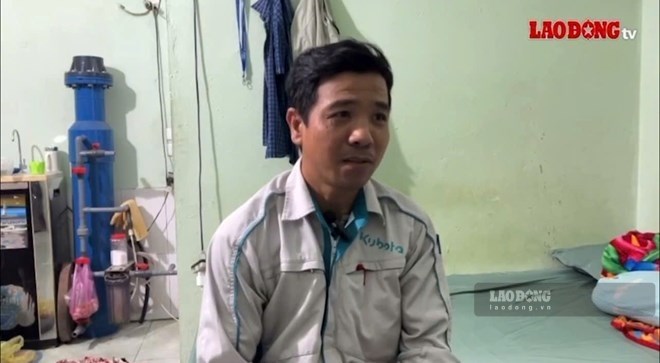
Meanwhile, Mr. Nguyen Huu Hau (from Nghe An) - who has been a worker at Thang Long Industrial Park (Hanoi) for more than 20 years - said that direct production workers can also start working very early, but by the age of over 40, they are already facing the risk of losing their jobs.
This group of workers has a relatively long period of social insurance contribution but is not old enough to retire, facing the risk of income interruption and affecting social security.
From that reality, Mr. Hau proposed to study a more flexible retirement mechanism for employees who have participated in social insurance for a long time but lost their jobs before reaching retirement age, in order to avoid interrupting the social insurance contribution process or having to wait many years to receive a pension.
From a legal perspective, Lawyer Dao Nguyen Thuat (Hanoi Bar Association) said that it is necessary to clearly distinguish between two cases to avoid understanding that for every sufficient number of years of social insurance contributions but early retirement, it is naturally deducted 2% of the pension each year.
According to Article 64 of the 2024 Law on Social Insurance, employees are entitled to a pension when they have paid social insurance for 15 years and meet the retirement age conditions, or fall into the case of being allowed to retire at a lower age as prescribed.
Meanwhile, Article 65 stipulates that employees with a social insurance contribution period of 20 years or more are entitled to early retirement due to reduced working capacity or having worked in a particularly heavy, hazardous, and dangerous profession or job with specific conditions attached.
For cases that meet the conditions to receive pensions according to Article 65, the benefit level is calculated according to Article 66 and reduced by 2% for each year of early retirement; the time of early retirement under 6 months is not reduced, from 6 months to less than 12 months is reduced by 1%.
Thus, it is not that employees who quit their jobs before age will be deducted 2% per year. If they have contributed enough years but are not old enough and do not fall into the case of early retirement according to Article 65, employees cannot receive pension immediately but must preserve the contribution period to wait for sufficient age.
From the above inadequacies, the problem that direct workers may encounter is that they are likely to lose their jobs at the age of over 40, they are facing the risk of interrupting the social insurance contribution process or having to wait many years to receive a pension, Lawyer Dao Nguyen Thuat proposed some solutions.
That is to study the early retirement mechanism for long-term social insurance contributors. Functional agencies can study to supplement a flexible retirement mechanism for groups of workers who have had a long period of social insurance contribution, for example from 30 years or more, but have not reached retirement age and have difficulty continuing to work.
The consideration needs to combine criteria on age, nature of work, working conditions and ability to maintain employment. At the same time, it is necessary to have a plan to calculate the pension level suitable for the early retirement period, ensuring the principle of contribution - benefit and balancing the Social Insurance Fund.
The lawyer also proposed to supplement a support mechanism for the transitional period. For people who have had a long period of social insurance contribution but lost their jobs and no longer have the ability to find suitable jobs, the State can study policies to support fixed-term income, support voluntary social insurance contributions or job connections so that they maintain their insurance participation process, avoiding social security disruptions.
Next is to strengthen communication and policy advice. It is necessary to help workers clearly distinguish cases of enjoying pensions, early retirement, preserving contribution time and choices to continue participating in voluntary social insurance, thereby proactively building appropriate social security plans.
See the original here